Card Issuing Platforms for Fintechs: What to Evaluate
Key Takeaways
- The global prepaid card and digital wallet market reached $2.13 trillion in 2026 and is projected to surpass $3 trillion by 2030 (GlobeNewsWire, March 2026) - making card issuing platform selection a decision with multi-year revenue implications.
- Migrating between card issuing platforms after launch typically costs 6-12 months of engineering time and requires renegotiating scheme relationships, making the initial evaluation critical.
- The ten evaluation dimensions that matter most are: BIN sponsorship model, card type coverage, scheme connectivity, regulatory jurisdiction coverage, API architecture, launch speed, branding control, fraud management, settlement infrastructure, and pricing transparency.
- Virtual card issuing platforms face distinct evaluation criteria around instant provisioning, tokenization support, and single-use card capabilities that physical card platforms may not address.
- Fintechs operating across multiple jurisdictions should evaluate whether a platform handles regulatory divergence (KYC thresholds, safeguarding rules, scheme compliance) through a single integration or requires separate implementations per market.
Choosing the right card issuing platform is one of the highest-stakes infrastructure decisions a fintech makes. The platform you select determines your time to market, your scheme relationships, your compliance posture, and your unit economics for every card you issue. Yet most evaluation processes focus on feature checklists rather than the architectural and commercial factors that actually determine whether a platform scales with your business or becomes a bottleneck.
This guide provides a structured evaluation framework for fintechs comparing card issuing platforms - covering the ten dimensions that separate infrastructure partners from infrastructure liabilities.
Contents
- Why Card Issuing Platform Selection Matters
- What a Card Issuing Platform Actually Does
- The 10-Dimension Evaluation Framework
- Card Issuing Platform Comparison Framework
- Virtual Card Issuing Platforms: Special Considerations
- Common Mistakes When Selecting a Card Issuing Platform
- Frequently Asked Questions
Why Card Issuing Platform Selection Matters
Card program migration is one of the most disruptive infrastructure changes a fintech can undertake. Unlike switching a payment gateway or updating a KYC provider, migrating your card issuing platform means renegotiating BIN sponsor relationships, re-certifying with Visa or Mastercard, re-issuing active cards, and rebuilding authorization logic. The switching cost is not just engineering time - it is scheme relationship risk, customer disruption, and regulatory re-approval.
The global card issuance market is growing rapidly. The prepaid card and digital wallet sector alone reached $2.13 trillion in 2026 (GlobeNewsWire, March 2026), and fintechs are increasingly launching card programs as their primary revenue driver rather than a secondary feature. This makes the initial platform decision a strategic commitment, not a procurement exercise.
Three factors make this decision irreversible in practice:
-
Scheme relationships are platform-bound. Your BIN, your scheme certifications, and your settlement flows are tied to the platform’s infrastructure. Changing platforms usually means changing your BIN - which means changing the first 6-8 digits of every card your customers hold.
-
Regulatory approvals are platform-specific. The compliance frameworks, KYC integrations, and safeguarding arrangements your regulator approved were built around your current platform’s architecture. A platform change triggers a regulatory review.
-
Card program economics compound over time. Interchange splits, per-card fees, and settlement timing accumulate into material revenue differences at scale. A pricing model that looks competitive at 10,000 cards may be punitive at 500,000.
What a Card Issuing Platform Actually Does
A card issuing platform sits between your fintech application and the card scheme infrastructure (Visa, Mastercard, UnionPay). It provides the technical, regulatory, and operational layer that enables you to issue branded cards without becoming a direct card scheme member.
The platform handles five core functions:
BIN sponsorship and scheme access. The platform provides access to a Bank Identification Number (BIN) through a licensed sponsor bank. This BIN appears as the first 6-8 digits of every card you issue. The BIN sponsor holds scheme membership and takes regulatory responsibility for the program. For a deeper explanation of BIN sponsorship mechanics, see our full guide to card issuing for fintechs.
Authorization and transaction processing. When a cardholder taps, swipes, or enters their card number online, the platform receives the authorization request, checks it against your program rules (balance, velocity limits, merchant category restrictions), and returns an approve or decline decision - typically within 200 milliseconds.
Clearing and settlement. After a transaction is authorized, the platform handles clearing (the exchange of transaction data between acquirer and issuer) and settlement (the movement of funds). Settlement timing - whether same-day, next-day, or T+2 - directly affects your cash flow and treasury operations.
Card lifecycle management. From provisioning (physical manufacturing or virtual card generation) through activation, PIN management, replacement, and deactivation, the platform manages every state change across the card’s lifecycle.
Compliance infrastructure. KYC/AML screening at card issuance, transaction monitoring against sanctions lists, suspicious activity reporting, and safeguarding of customer funds where required by regulation.
The 10-Dimension Evaluation Framework
1. BIN Sponsorship Model
The BIN sponsorship arrangement is the foundation of your card program. Two models exist:
Managed BIN sponsorship - the platform provides access to a BIN sponsor as part of the service. You interact with the platform; the platform manages the sponsor bank relationship. This is faster to launch but limits your control over the sponsor relationship.
Direct BIN sponsorship - you bring your own BIN sponsor or negotiate directly with a sponsor bank, using the platform only for technical infrastructure. This gives you more control and potentially better economics, but requires more regulatory and commercial sophistication.
Mastercard’s BIN Sponsor Plus programme, launched in 2026 in the UK, formalizes the compliance accountability between sponsors and fintechs - making the quality of the sponsor relationship a differentiator, not just a checkbox.
What to evaluate: Does the platform lock you into a single BIN sponsor, or can you bring your own? Can you migrate sponsors without re-platforming? What happens to your BIN if the sponsor relationship ends?
2. Card Types Supported
Not every card issuing platform supports every card type. The four categories to evaluate:
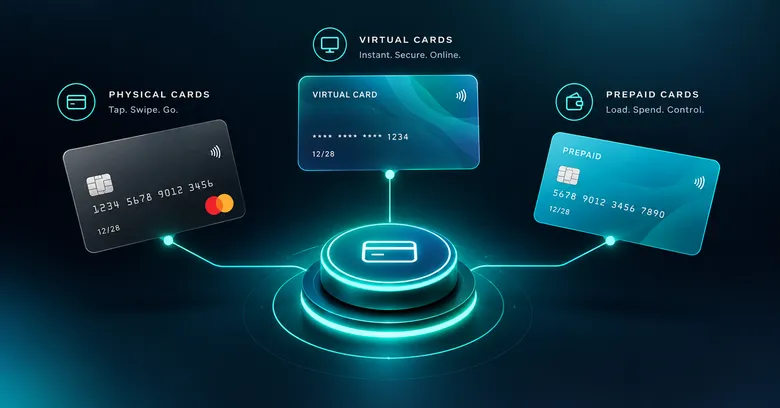
- Prepaid cards - stored value, e-money regulated, tiered KYC
- Debit cards - bank account-linked, full KYC, ATM and direct debit capable
- Virtual cards - instant provisioning, configurable limits, single-use or recurring
- Tokenized cards - Apple Pay, Google Pay, and in-app provisioning via card scheme tokenization services
A platform that handles prepaid only will constrain your product roadmap if you later need debit or tokenized wallet provisioning. Evaluate against your 18-month product plan, not just your launch product.
3. Scheme Connectivity
Evaluate which card networks the platform connects to and how:
- Visa and Mastercard are table stakes for most markets
- UnionPay matters for APAC-focused programs
- Domestic schemes (EFTPOS in Australia, NETS in Singapore) may be required for local acceptance
Critically, evaluate whether the platform holds direct scheme certifications or operates through a third-party processor. Direct certification gives you more control over scheme features (installments, card-on-file tokenization, real-time push payments) and avoids an additional intermediary in the authorization chain.
4. Regulatory Coverage and Multi-Jurisdiction Licensing
A card issuing platform’s regulatory footprint determines where you can launch. Evaluate:
- Which jurisdictions does the platform (or its BIN sponsors) hold licenses in?
- Does the platform handle regulatory divergence - different KYC thresholds, fund safeguarding rules, and consumer protection requirements - through a single integration?
- How does the platform handle ongoing regulatory changes? Regulatory calendar awareness and proactive compliance updates are markers of a mature platform.
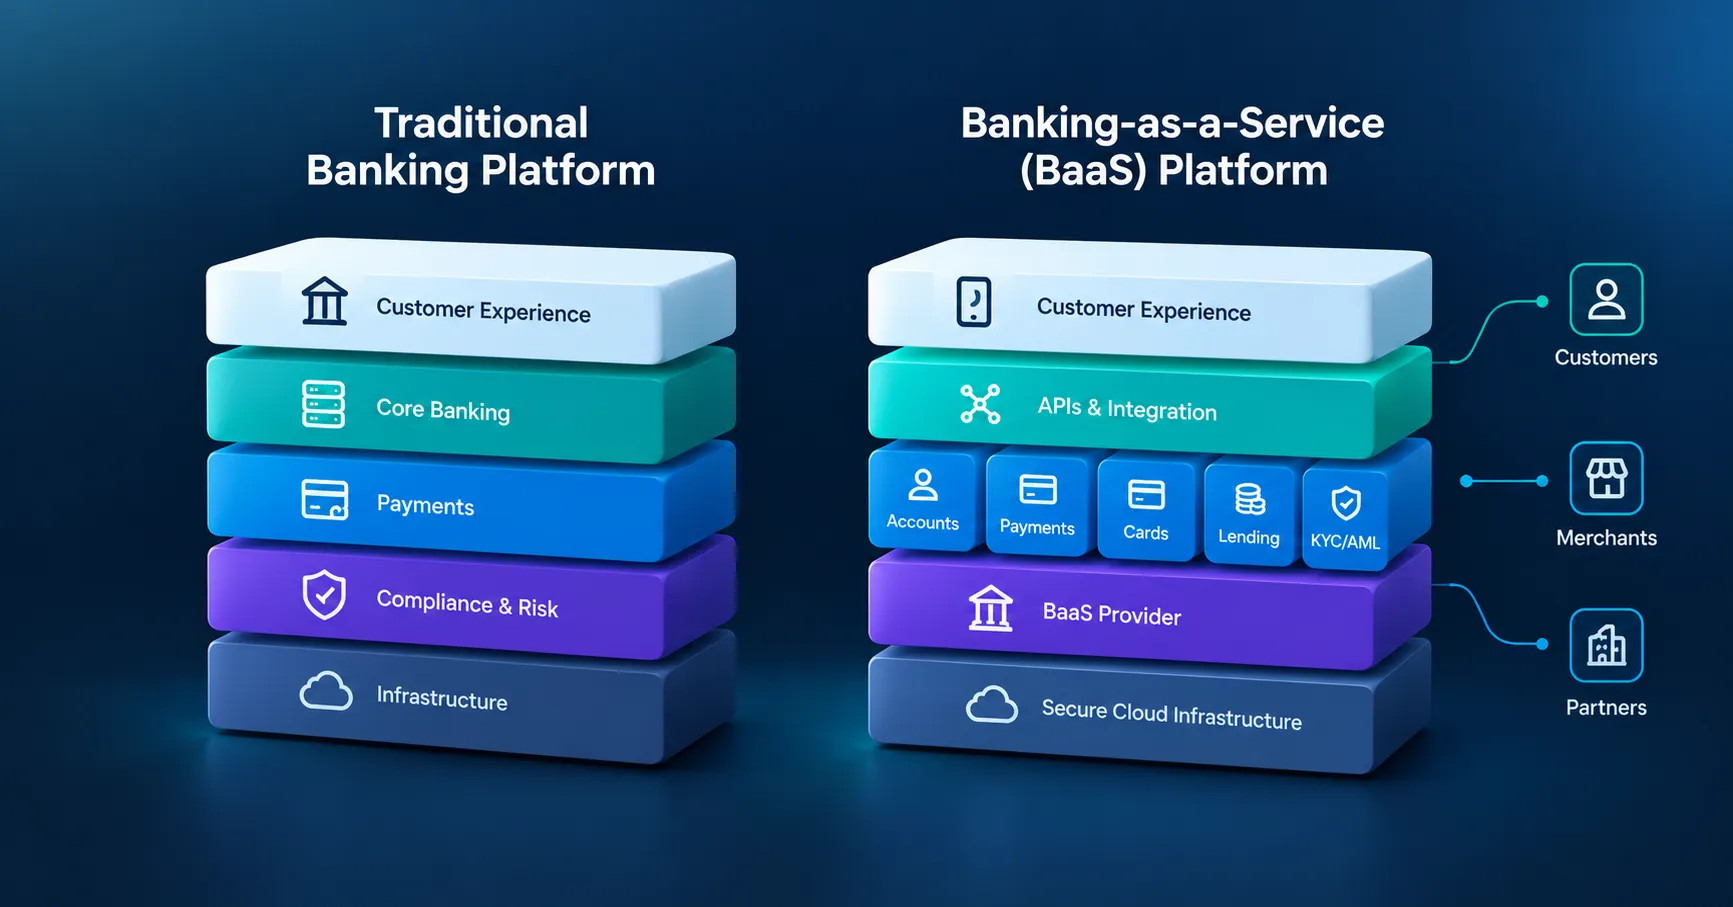
For fintechs operating through a Banking as a Service model, the card issuing platform’s regulatory infrastructure should integrate with the broader BaaS compliance framework rather than operating as a standalone compliance silo.
Spending months integrating separate providers for cards, payments, and compliance? Aerapass combines card issuance, global payments, and multi-jurisdiction licensing through a single API integration - so your engineering team ships a card program, not a patchwork of vendor contracts. See how Aerapass simplifies card issuance.
5. API Architecture
The technical integration is where evaluation often starts, but it should be assessed in context of the other nine dimensions:
- REST APIs with comprehensive documentation, versioning, and backward compatibility guarantees
- Webhook infrastructure for real-time event notifications (authorization, settlement, disputes, card status changes)
- Sandbox environment with realistic test scenarios, scheme simulators, and test card numbers
- SDK availability in your engineering team’s primary languages
- Rate limits and latency SLAs - authorization endpoints should guarantee sub-200ms response times at the 99th percentile
Red flag: A platform that offers sandbox access only after contract signing is a platform that does not want you to evaluate its API quality before committing.
6. Time to First Card Issued
Launch speed is a function of the platform’s pre-built infrastructure, not just its API documentation:
- How long from contract signing to first card issued in production?
- What dependencies sit on the critical path (scheme approval, BIN sponsor onboarding, compliance review)?
- Does the platform provide a pre-approved program template that accelerates scheme certification?
Platforms with managed BIN sponsorship and pre-certified program templates can deliver first cards in weeks. Platforms requiring you to source your own sponsor and complete scheme certification from scratch typically take 3-6 months.
7. Card Personalization and Branding Control
Your card is your brand artifact. Evaluate the degree of branding control:
- Physical card design - metal, plastic, recycled materials, custom shapes
- Virtual card appearance - colors, logos, dynamic card art
- Card carrier and packaging design
- Co-branded arrangements (your brand + scheme logo + sponsor bank)
- Push provisioning appearance in Apple Wallet and Google Pay
8. 3DS and Fraud Management
Strong Customer Authentication (SCA) and fraud management are regulatory requirements in most markets. Evaluate:
- Does the platform support 3D Secure 2.x with frictionless authentication flows?
- Is transaction-level fraud scoring included or an additional module?
- Can you configure custom fraud rules (velocity checks, merchant category blocks, geographic restrictions)?
- Does the platform provide dispute management and chargeback handling?
- If your program also requires payment acceptance, does the platform offer hosted payment pages with branded checkout that handles 3DS challenges, tokenized card storage, and local payment methods - or will you need a separate acquirer integration?
9. Settlement and Reconciliation
Settlement infrastructure directly impacts your treasury operations:
- Settlement frequency (real-time, same-day, T+1, T+2)
- Multi-currency settlement capabilities
- Reconciliation file formats and delivery schedule
- Integration with your payments infrastructure and accounting systems
10. Pricing Model
Card issuing platform pricing typically includes several components. Evaluate each for transparency and scalability:
- Setup fees - one-time costs for program design, scheme certification, and integration
- Monthly platform fees - fixed or tiered by active card count
- Per-card issuance fees - physical vs virtual, domestic vs international
- Per-transaction fees - authorization, clearing, and settlement charges
- Interchange revenue share - the split of interchange income between you, the platform, and the BIN sponsor
Red flag: Platforms that quote a single “per-card” price without breaking out interchange splits are often capturing the majority of your interchange revenue.
Card Issuing Platform Comparison Framework
Use this framework to structure your evaluation conversations with potential platform partners:
| Dimension | What to Ask | Red Flags |
|---|---|---|
| BIN sponsorship | ”Can we migrate sponsors without re-platforming?” | Locked into a single sponsor with no migration path |
| Card types | ”Which card types are production-ready vs roadmap?” | Virtual cards listed as “coming soon” without a date |
| Scheme connectivity | ”Do you hold direct Visa and Mastercard certifications?” | Scheme access through a fourth-party processor |
| Regulatory coverage | ”Which jurisdictions can we launch in within 90 days?” | Single-jurisdiction platform with “plans to expand” |
| API architecture | ”Can we access your sandbox before signing a contract?” | No sandbox access pre-contract; no webhook support |
| Launch speed | ”What is your median time to first card issued?” | No reference customers willing to confirm timelines |
| Branding control | ”Can we see card samples from current programs?” | Design restrictions beyond scheme brand guidelines |
| Fraud management | ”Is 3DS 2.x included or a separate module?” | Basic fraud rules only; no custom rule configuration |
Source: Evaluation framework derived from Mastercard BIN Sponsor Plus partner requirements (2026) and Visa Fintech Fast Track program criteria (2025)
Virtual Card Issuing Platforms: Special Considerations
Virtual card issuing platforms share the same foundational requirements as physical card platforms but introduce additional evaluation criteria specific to digital-first card programs.
Instant provisioning at scale. A virtual card issuing platform must provision cards in real time - not minutes, not batches. Evaluate whether the platform’s provisioning API supports burst issuance (hundreds of cards per second) for use cases like expense management, where an employee might need a new virtual card for every vendor.
Single-use and multi-use card controls. B2B virtual card programs often require single-use cards that auto-deactivate after one transaction. Evaluate whether single-use logic is handled at the platform level or requires your application to manage card deactivation.
Push provisioning to mobile wallets. Virtual cards that cannot be added to Apple Pay or Google Pay are functionally limited for consumer use cases. Evaluate whether the platform supports in-app provisioning (where the card appears in the wallet without the user manually entering card details).
Dynamic spend controls. Virtual card issuing platforms should support real-time spend limit adjustments, merchant category restrictions, and time-based controls (cards that are active only during business hours, for example). These controls are core to B2B expense management and corporate card programs.
Tokenization for recurring payments. For subscription and marketplace platforms issuing virtual cards, evaluate whether the platform supports network tokenization (Visa Token Service, Mastercard Digital Enablement Service) to maintain card-on-file relationships when virtual cards are replaced or renewed.
Common Mistakes When Selecting a Card Issuing Platform
Evaluating the API before evaluating the license. A technically excellent platform with limited regulatory coverage will constrain your geographic expansion. Start with regulatory footprint, then evaluate the technology.
Ignoring interchange economics. The interchange split between you, the platform, and the BIN sponsor is often the largest variable in card program profitability. A platform with low per-card fees but unfavorable interchange splits may be more expensive at scale than a platform with higher upfront costs and transparent interchange sharing.
Treating virtual and physical as the same evaluation. The infrastructure required for instant virtual card provisioning is architecturally different from physical card manufacturing and fulfillment. A platform strong in physical card programs may lack the real-time capabilities required for virtual-first products.
Selecting based on launch speed alone. The fastest platform to launch is not necessarily the best platform to scale. Evaluate whether the platform’s architecture supports your 18-month product roadmap - additional card types, new jurisdictions, custom fraud rules, and multi-currency settlement.
Not testing the dispute and chargeback flow. Every card program generates disputes. Test the dispute management workflow in sandbox before committing - including notification timing, evidence submission, and resolution tracking. A platform with poor dispute handling creates operational overhead that compounds at scale.
Frequently Asked Questions
What is a card issuing platform and how does it differ from a payment processor?
A card issuing platform provides the infrastructure for creating and managing branded payment cards - including BIN sponsorship, scheme connectivity, card provisioning, and authorization processing. A payment processor handles the acquirer side: accepting payments from merchants. The issuing platform creates the card; the payment processor accepts it. Some infrastructure providers offer both, but the evaluation criteria, regulatory requirements, and commercial models are distinct.
How long does it typically take to launch a card program on a new platform?
With managed BIN sponsorship and pre-certified program templates, fintechs can issue their first cards within 4-8 weeks. Programs requiring custom scheme certification, direct BIN sponsor onboarding, or multi-jurisdiction regulatory approval typically take 3-6 months. The critical path is usually scheme approval and BIN sponsor due diligence, not technical integration.
What is the difference between a credit card issuing platform and a prepaid card issuing platform?
A credit card issuing platform must integrate with credit decisioning systems, credit bureau reporting, and lending-specific regulatory frameworks. It requires the issuer (or its sponsor bank) to hold a lending license and maintain capital reserves against credit exposure. A prepaid card issuing platform operates under stored value or e-money regulations, requires fund safeguarding rather than capital adequacy, and does not involve credit risk assessment. The technical and regulatory infrastructure differs substantially.
Can a fintech switch card issuing platforms after launch?
Yes, but it is operationally complex and commercially disruptive. Migration typically requires renegotiating BIN sponsor relationships (which may mean changing your BIN and re-issuing all active cards), re-certifying with Visa or Mastercard, and rebuilding authorization logic. Most migrations take 6-12 months. The cost of migration underscores why the initial platform evaluation should be thorough.
What should a fintech look for in a virtual card issuing platform specifically?
Beyond the standard evaluation dimensions, virtual card issuing platforms should be assessed on: instant provisioning speed (real-time, not batch), single-use card support, push provisioning to Apple Pay and Google Pay, dynamic spend controls (real-time limit adjustments, merchant category restrictions, time-based activation), and network tokenization for card-on-file continuity. B2B-focused platforms should also support bulk issuance and delegated card management for corporate administrators.
Worried about outgrowing your card issuing platform? Aerapass is licensed in six jurisdictions and supports BIN sponsorship, custom 3DS flows, and configurable spend controls through one integration - built for fintechs that need to scale across markets without re-platforming. See how Aerapass scales with your card program.
Regulatory Disclosure: Aerapass financial services are provided through Aerapass, a Major Payment Institution licensed by the Monetary Authority of Singapore and regulated across four jurisdictions (Hong Kong, Singapore, Australia, and Canada). This article is for educational purposes only and does not constitute financial, legal, or regulatory advice. Regulatory requirements vary by jurisdiction and change over time. Companies evaluating card issuing infrastructure should consult qualified legal and compliance advisors in each market they intend to serve.
The content on this page is produced by Aerapass for general informational purposes only and does not constitute financial advice, investment advice, or any other form of professional advice. Aerapass is a technology platform provider serving financial institutions, wealth managers, and fintech companies. Before making any financial decision, you should consult with a qualified, licensed financial advisor who can take your individual objectives and circumstances into account.